The News Vista is dedicated to delivering accurate, timely, and unbiased news to keep our readers informed. We cover a wide range of topics including current affairs, politics, business, technology, and more.
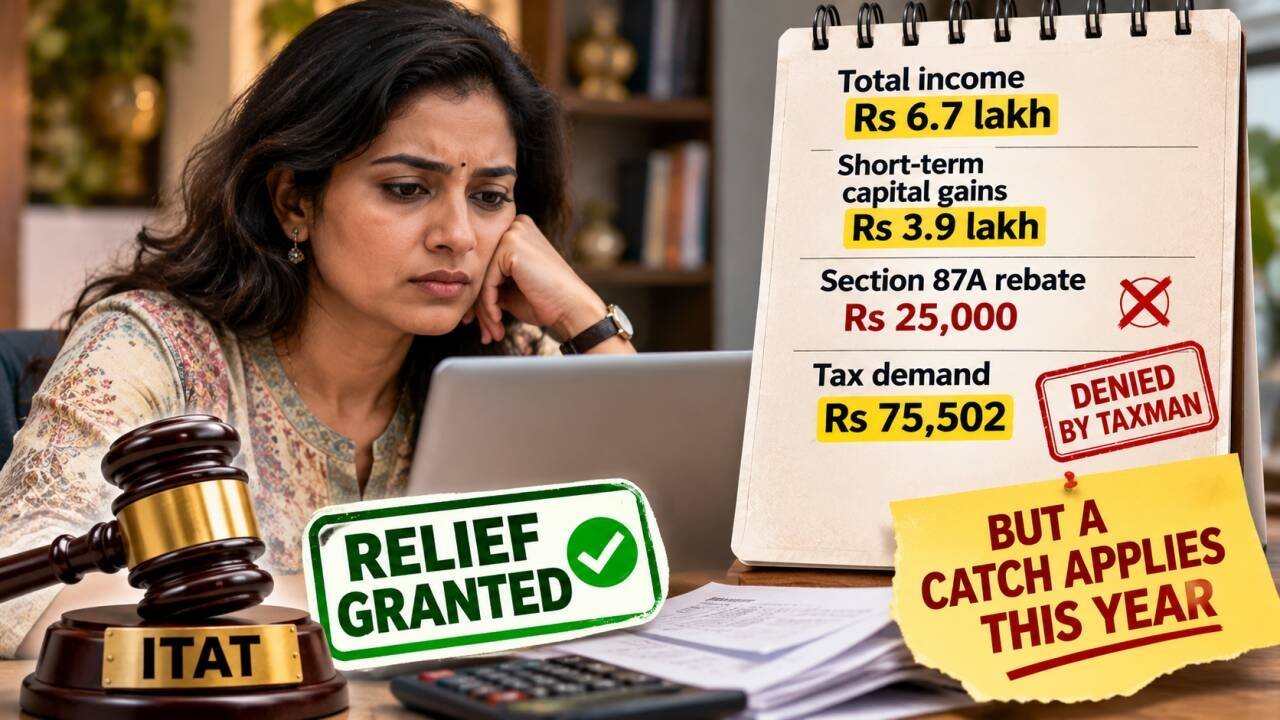
A woman filed her income tax return for assessment year 2025-26, declaring a total income of Rs 6,77,511. This included short-term capital gains of Rs 3,97,511 arising from the transfer of listed equity shares. Such gains are taxable u/s 111A of the Act at a special rate of tax. She opted for the new tax regime under Section 115BAC(1A) and claimed a rebate of Rs 25,000 under Section 87A.